
I have been living in Mexico since 2011, and during this time I managed to build my credit history, destroy it, and rebuild it again from scratch. In this post, I will share my experience and how to build a credit history in Mexico as a foreigner.
Moving to Mexico doesn’t automatically bring your financial history with you.
You might have spent 15 or 20 years building excellent credit in another country, have several credit cards, or even own a home.
Then you arrive in Mexico and discover something frustrating:
Mexican financial institutions may have very little local information about you.
In many ways, you’re starting again.
I’ve lived in Mexico for many years, and one thing I’ve learned is that building a financial life here happens gradually.
You establish your documents.
You open bank accounts.
You obtain your RFC.
And eventually, you begin developing a Mexican credit history.
The good news is that you don’t need to start with a huge credit limit.
Your first objective should simply be to establish a clean, consistent payment history.
Here’s how I would approach it.
Important
This article is educational and does not constitute individualized financial advice. Credit-card requirements, interest rates, fees, and approval criteria vary between financial institutions and can change.
Does Mexico Have Credit Scores?
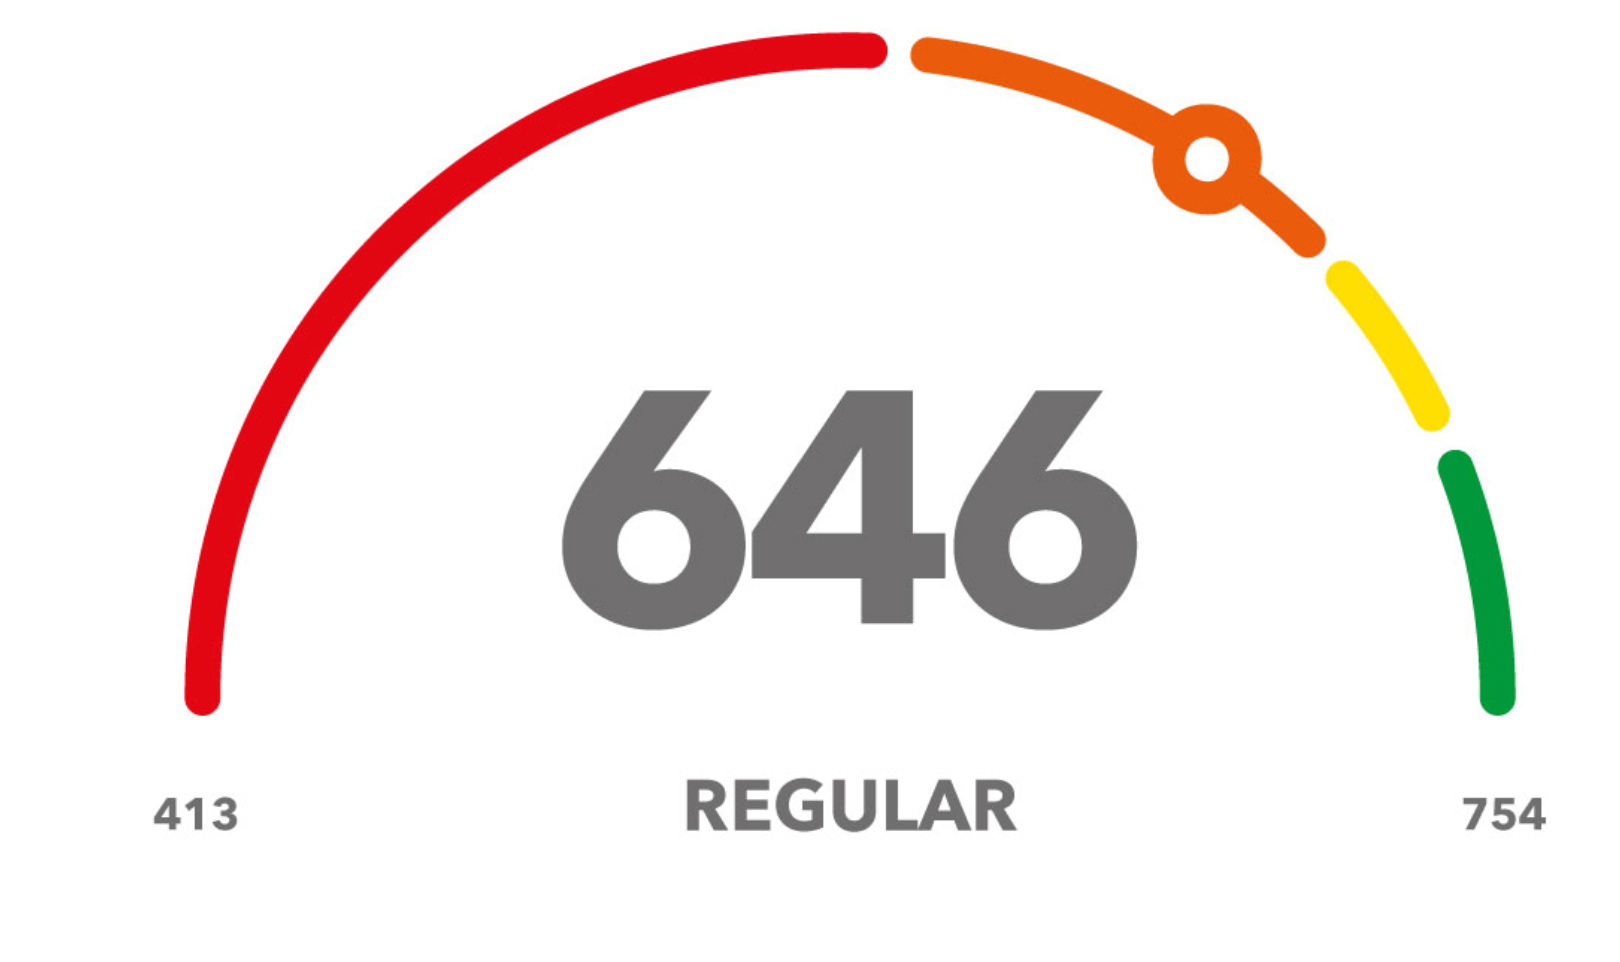
Mexico has credit-reporting companies known as Sociedades de Información Crediticia.
One of the best-known is Buró de Crédito.
An important misconception is that being “in Buró” automatically means you’ve done something wrong.
It doesn’t.
Buró de Crédito explains that your credit history begins when you obtain credit, and your report can contain both timely and late payments.
In other words:
Having a credit history isn’t bad. Having a bad payment history is the problem.
Your Reporte de Crédito Especial can contain information such as:
- Credit accounts
- Opening dates
- Payment history
- Current balances
- Credit limits
- Previous credit inquiries
Buró de Crédito currently says consumers can obtain a Reporte de Crédito Especial free once every 12 months.
Does Your Foreign Credit History Transfer to Mexico?
Generally, don’t assume that the excellent credit profile you built abroad will simply appear in Mexico.
A Mexican lender making a lending decision will usually be interested in the information available to it through Mexico’s financial and credit-reporting ecosystem, together with its own underwriting requirements.
That’s why newcomers can face an annoying problem:
You need credit history to qualify for credit, but you need credit to create credit history.
The solution is to start small.
How to Build Credit in Mexico as a Foreigner
Here are the 8 steps you can follow to build credit in Mexico as a foreigner.
Step 1: Establish Your Mexican Financial Identity
Before worrying about credit cards, get your basic financial infrastructure organized.
Ideally, you should have your:
- Passport
- Mexican residence documentation
- CURP
- RFC, where applicable
- Mexican address
- Proof of address
- Mexican phone number
- Mexican bank account
Consistency is extremely important.
Make sure your name is represented consistently across your immigration documents, CURP, RFC, and banking information.
This is especially important for foreigners whose names don’t follow typical Mexican naming conventions.
How to Open a Bank Account in Mexico as a Foreigner
How to Get an RFC in Mexico as a Foreigner
Step 2: Establish a Relationship With a Mexican Bank
I would start with a checking or debit account.
Use it normally.
Receive income where appropriate.
Pay bills.
Make transfers.
Maintain a reasonable balance.
This doesn’t guarantee that the bank will approve you for credit, but it establishes a relationship with the institution.
Over time, your bank may begin showing you credit offers through its app or other channels.
Don’t feel pressured to accept every offer.
You need one useful credit product, not ten.
Step 3: Start With One Manageable Credit Product
Your first Mexican credit card doesn’t need to be glamorous.
You don’t need airport lounges.
You don’t need a giant credit limit.
You don’t need a premium metal card.
You need an account that you can manage responsibly.
If a traditional unsecured card isn’t available to you yet, investigate whether regulated institutions offer starter products appropriate to your circumstances.
Before applying, examine:
- Annual fee
- Interest rate
- CAT
- Late-payment fees
- Minimum income requirements
- Credit limit
- Whether the institution reports payment behavior to a Mexican credit bureau
Don’t apply blindly for every card you see.
Step 4: Use the Card for Normal Expenses
Once you receive your first card, don’t suddenly start spending more.
Instead, move expenses you already have onto the card.
For example:
- Mobile phone
- Groceries
- Fuel
- Internet
- Streaming subscriptions
- Small household purchases
Suppose you normally spend 2,500 MXN each month on expenses like these.
Put those purchases on the card.
Then pay the statement correctly.
You’re not creating additional spending.
You’re simply changing how you pay for spending that already exists.
Step 5: Learn the Difference Between the Minimum Payment and the Payment to Avoid Interest
This is extremely important.
Mexican credit-card statements typically show different payment amounts.
Two you’ll frequently see are
Pago mínimo
and
Pago para no generar intereses
They are not the same thing.
CONDUSEF warns that paying only the minimum can cause your debt to take much longer to repay. It describes the “pago para no generar intereses” as the amount that must be paid by the deadline to avoid interest on the relevant balance.
My approach is simple
Whenever possible, pay the full amount required to avoid interest.
Don’t turn credit-building into an excuse for expensive consumer debt.
Step 6: Never Miss the Payment Date
Your payment history matters.
Buró de Crédito’s reporting distinguishes between accounts paid on time and accounts with various levels of delinquency.
A small forgotten payment can create unnecessary problems.
Set:
- Calendar reminders
- App notifications
- Automatic payments where appropriate
I prefer systems that don’t depend entirely on memory.
Step 7: Don’t Apply for Too Much Credit at Once
When you’re starting, it can be tempting to apply everywhere.
One bank rejects you.
So you try another.
Then another.
Then another.
Be careful.
Your credit report can show inquiries from lenders, and Buró de Crédito says credit inquiries remain visible on the Reporte de Crédito Especial for 24 months.
Build slowly.
Your goal isn’t
“How many cards can I get?”
It’s
“How strong and useful can I make my financial profile?”
Step 8: Check Your Credit Report
Once you’ve begun establishing credit, check what is actually being reported.
Buró de Crédito’s Reporte de Crédito Especial can show your accounts, balances, payment history, credit limits, and inquiries.
The first report during 12 months is currently available for free through Buró de Crédito.
Check for:
- Accounts you recognize
- Correct personal information
- Correct credit limits
- Payment status
- Unknown inquiries
- Accounts you never opened
This isn’t only about borrowing.
It’s also a form of financial security.
What If You Find an Error?
Don’t ignore it.
Buró de Crédito has a formal reclamation process for information you believe is incorrect.
Keep documentation supporting your position, such as statements, payment confirmations, and account-closing documents.
How Long Does It Take to Build Credit in Mexico?
There isn’t a universal number of months that guarantees approval.
Every lender has its own underwriting criteria.
Instead of obsessing about a particular score after 30 or 60 days, focus on the behaviors you control:
Pay on time.
Keep your finances organized.
Don’t overborrow.
Avoid unnecessary applications.
Review your credit report periodically.
Give the system time to accumulate information.
Should You Carry a Balance to Build Credit?
You do not need to deliberately pay interest simply to demonstrate that you can use credit.
Using your account and paying it responsibly can create payment history without intentionally carrying expensive revolving debt.
This is one of the most damaging credit myths.
Paying interest isn’t an achievement.
Building a record of responsible financial behavior is.
What I Would Do If I Were Starting Again
My strategy would be very simple:
Month 1: Establish my Mexican bank account and financial documents.
Month 2–3: Look for one appropriate starter credit product.
Following months: Put a few recurring expenses on it and pay correctly every month.
Later: Check my Mexican credit report and verify that everything is accurate.
Only then: Consider whether another card or larger credit line would actually improve my financial system.
There is no prize for having the most credit cards.
Final Thoughts
Building credit in Mexico as a foreigner takes patience.
Don’t worry if your first credit limit is small.
Your first card is simply the beginning of a record.
Use it responsibly.
Pay on time.
Monitor your report.
And gradually allow your Mexican financial history to develop.
Your goal isn’t debt.
Your goal is financial flexibility.
Credit can eventually make certain financial transactions easier, but it should remain a tool inside your broader wealth-building strategy, not the strategy itself.
Continue Reading
The First 5 Financial Things to Do When You Arrive in Mexico as a Foreigner
How to Open a Bank Account in Mexico as a Foreigner
How to Get an RFC in Mexico as a Foreigner
Do Expats Pay Taxes in Mexico?
Download the Expat Wealth Starter Kit